Quarterly Market Update True North Market Commentary
True North’s perspective on the merger and acquisition markets is shaped by first understanding the market for transactions of all sizes, followed by a sharp focus on the lower middle market transactions between $10 million and $250 million in enterprise value.
North American Market – Q2 2026
The North American Market across all buyers (PE, Family Office, Public, Private) showed slightly decreased activity and deal volume from Q1 2026, but still showed robust deal making compared to a year ago. Some of that dip is seasonal: second-quarter deal counts in North America have trailed the first quarter every year since 2021. In Q1 2026, deal volume was driven by very large transactions.
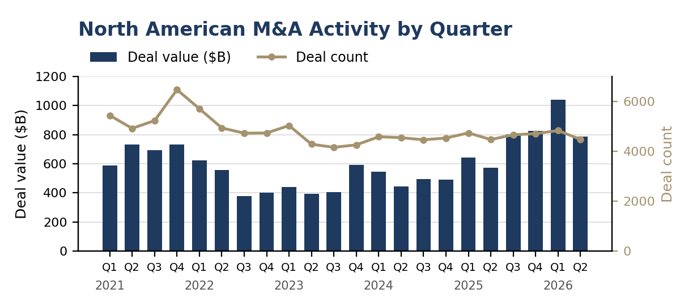
Source: PitchBook Q2 2026 Global M&A Report, as of June 30, 2026, North America, including estimated values
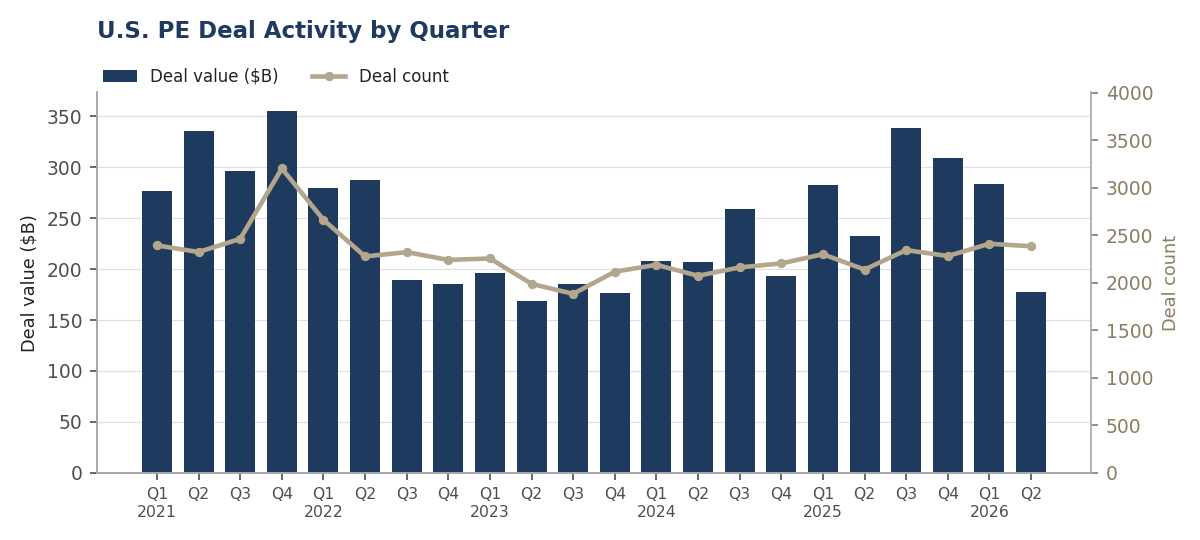
U.S. Private Equity Market – Q2 2026
For U.S. PE transactions of all sizes, Q2 2026 was a quarter of smaller checks, not fewer deals. Deal count rose 11.5% year-over-year from Q2 2025, but total deal value fell 37.5% from Q1 to $177 billion, the lowest quarterly level since late 2023. Different from the broad North American analysis above, which included all types of buyers, PE Buyers stayed busy; what disappeared was the appetite for large, debt-heavy transactions.
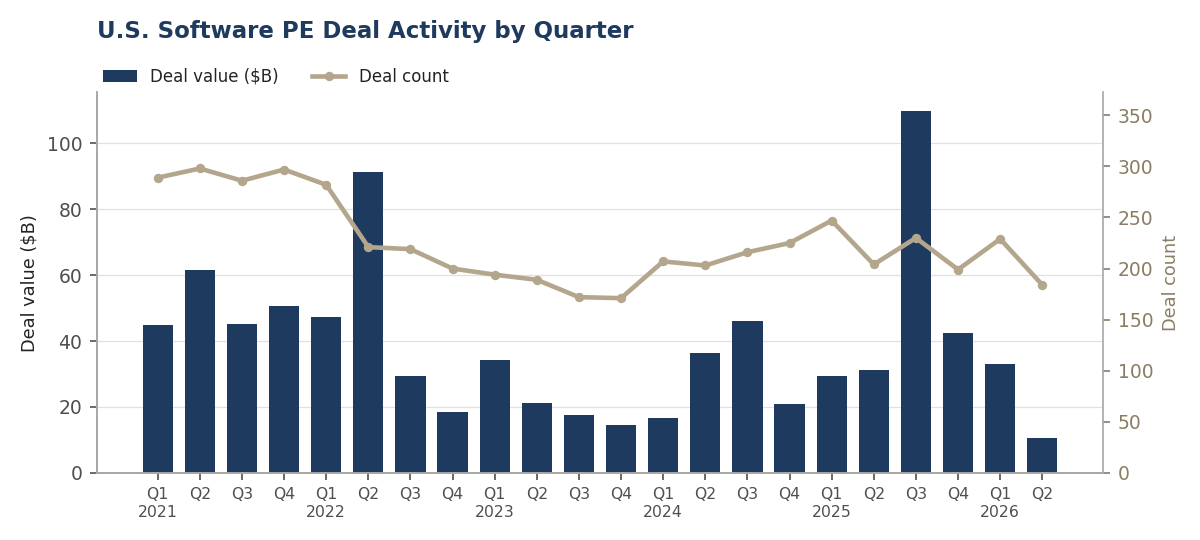
Two forces defined the quarter: energy prices and rate expectations tied to the Middle East conflict, and the AI-driven reset in software valuations. The Fed held rates steady in June with half the committee projecting a hike, and that hike arrived on September 16, when the Fed raised its target range 25 basis points to 3.75% to 4.00%. Through the quarter, capital kept moving toward smaller transactions, add-on acquisitions, and businesses built on physical operations. Further rate activity could promote interest in lower middle market transactions. No segment retrenched harder than software, where deal value fell 65.7% year over year as buyers reassess how AI will reshape the sector’s economics.
Q2 2026 closed with approximately 2,384 U.S. private equity transactions. Sponsors stayed active but wrote much smaller checks: the median transaction held near recent highs while the average fell by nearly half. Add-ons remained the dominant buyout strategy at roughly 75% of all buyouts, platform buyout count fell by a third, and growth and expansion investing was the only category to increase. We read this as buyers repricing risk, not leaving the market: capital is concentrating in smaller, less leveraged, buy-and-build structures, and buyer appetite for well positioned middle market companies remained intact even as headline deal value fell.
What this means for Business Owners: The pullback was concentrated in the largest, most debt-dependent transactions. Buyer appetite for well-prepared middle market companies, whether as add-ons, new platforms, or growth investments, stayed intact. Clean financials, a clear growth story, and management continuity remain the price of entry. If your business is built around physical operations (manufacturing, distribution, infrastructure, utilities-adjacent services), sponsor demand remains strong. If your business sells software, expect a more measured buyer set.
Middle Market Valuations: What Your Business is Worth
GF Data’s second quarter report, released in late August, shows a steady lower middle market. Contributing sponsors closed 85 deals in the $10 million to $500 million enterprise value range, matching the first quarter, which GF Data has revised up to 85 deals from the 80 first reported. That puts the first half at 170 deals, roughly 10% ahead of last year’s pace. The quarterly average slipped to 7.0x EBITDA from 7.3x, but that drop is mostly mix: nothing closed above $250 million this quarter, and pricing inside each size band held close to where it was in Q1. The first-half average sits at 7.1x, essentially where both 2024 and 2025 finished.
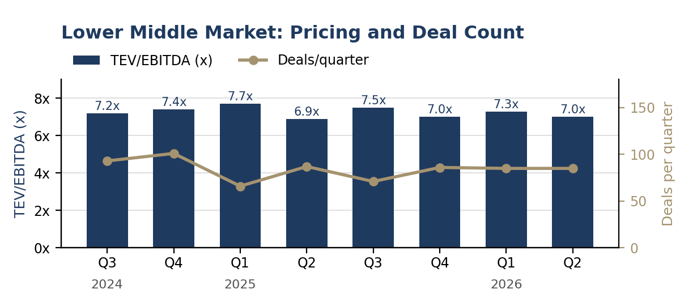
Source: GF Data Second Quarter 2026 M&A Report, August 2026
The premium buyers pay for above-average financial performance narrowed to about 5%, and platform and add-on pricing, which had split wide apart in Q1, came back together at 7.1x year to date. Leverage moved the other way: total debt on platform buyouts eased to 2.9x EBITDA from 3.4x, with senior debt at 2.0x, a reminder that lenders remain selective even where pricing is firm.
Healthcare services again topped the table, though its 7.7x year-to-date average is a step down from the 8.5x we noted at the first-quarter reporting, and business services recovered to 7.5x on 52 first-half deals, roughly double its first-quarter count. Manufacturing held near 7.1x on steady volume, while distribution trailed at 6.0x.
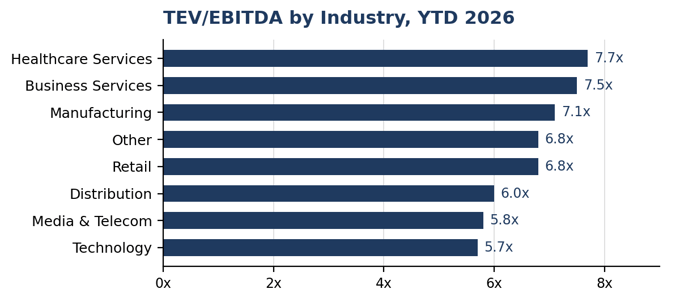
Source: GF Data Second Quarter 2026 M&A Report, August 2026
What this means for Business Owners: Buyers can no longer count on leverage or multiple expansion to carry their returns, so underwriting leans on operating performance and organic growth prospects. Expect diligence to concentrate on the durability of revenue, the credibility of the first two years of your projections, and the depth of your management team.
April 2026
TRUE NORTH PLUMBING AND HEATING CLIENT SELLS TO STRATEGIC PARTNER
True North Strategic Advisors, LLC represented a Midwest-based Plumbing & Heating service client that was acquired by a strategic partner. This transaction is reflective of considerable activity in the residential and commercial home services market, with robust activity in the Plumbing, Heating, and Electrical sector.
May 2026
A. HATTERSLEY & SONS | FORT WAYNE, IN
Chicago-based Foundral acquired A. Hattersley & Sons, a historic Fort Wayne mechanical contractor, expanding Foundral’s Midwest mechanical services network and growing its combined workforce to roughly 350 employees. The deal continues the consolidation of commercial mechanical, plumbing, and HVAC contractors by buy-and-build platforms seeking established customer relationships and skilled trade workforces. Terms were not disclosed.
Source: Inside INdiana Business
June 2026
TALLMAN EQUIPMENT | INDIANA
Platte River Equity acquired Tallman Equipment, an Indiana distributor of tools and equipment serving the electric utility and linework segments, with services spanning tool repair, fiberglass testing, rope fabrication, and rentals. The deal is Platte River’s 100th acquisition and reflects sustained sponsor demand for distribution businesses tied to grid and utility spending. Terms were not disclosed.
Source: Industrial Distribution
July 2026
FORT WAYNE METALS | FORT WAYNE, IN
Axel Johnson Inc., a New York-based, family-owned investment company, completed its acquisition of Fort Wayne Metals, the Fort Wayne-based manufacturer of precision wire and wire-based materials for medical devices and other demanding applications, one day after quarter end. The transaction places one of northeast Indiana’s flagship advanced manufacturers with a long-term, permanent-capital owner. Terms were not disclosed.
Source: Inside INdiana Business